Rate Hikes Coming in 2027: What BC Homebuyers Should Know Now
Markets are pricing in three BoC rate hikes by mid-2027. Here's what that means for BC real estate affordability.
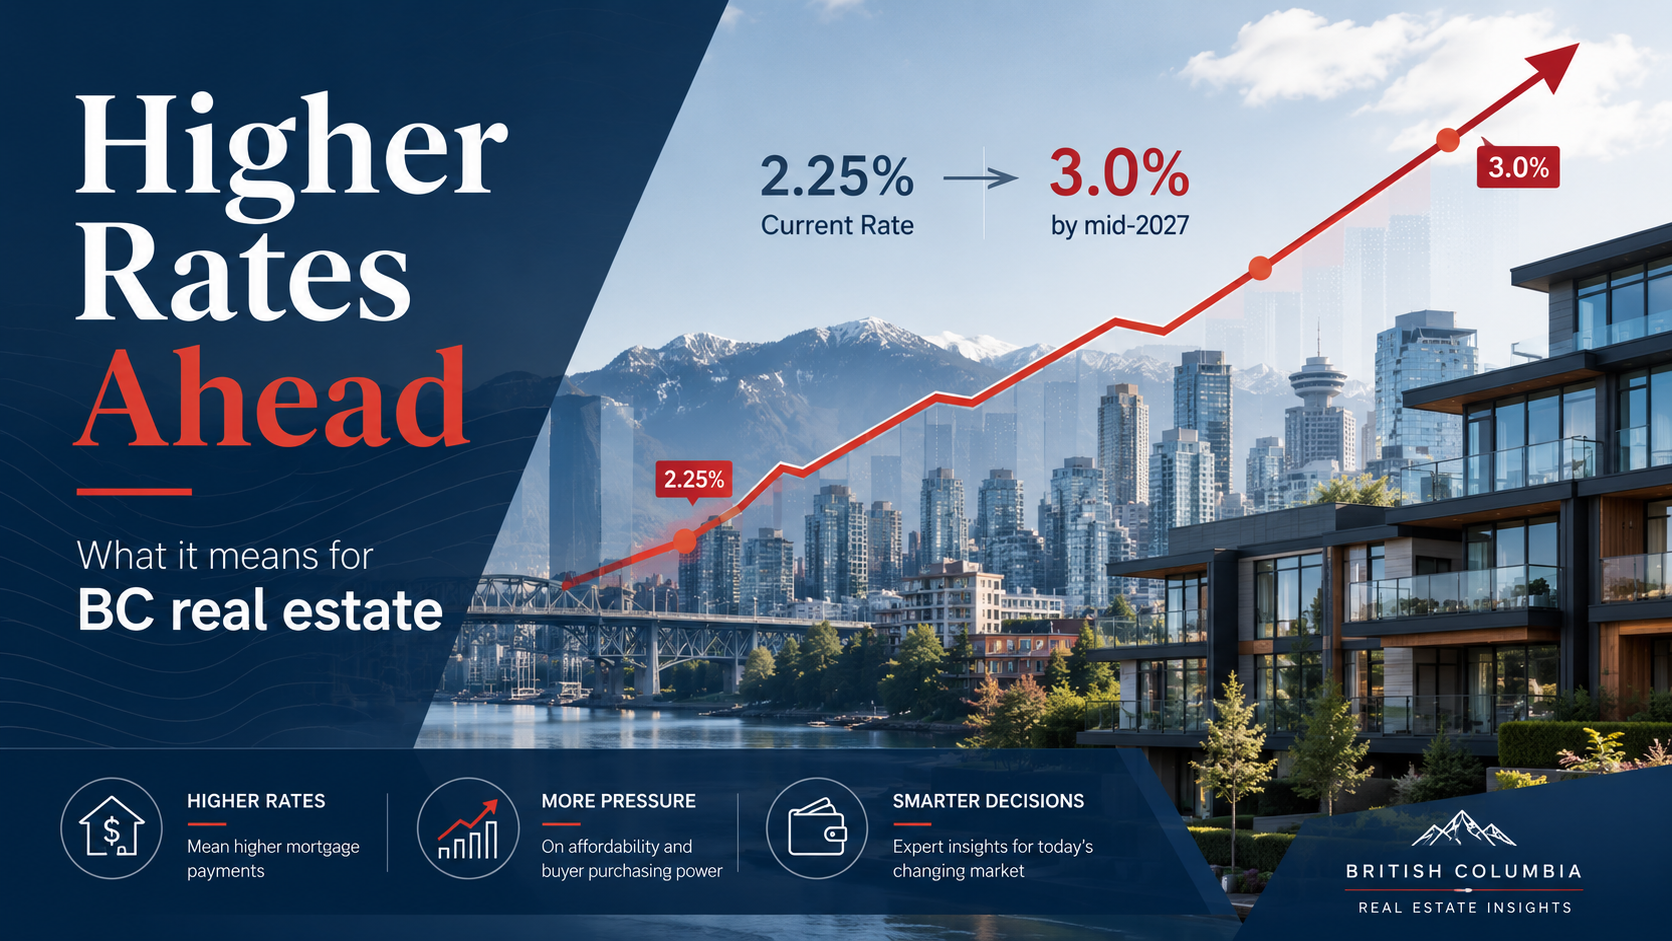
The Bank of Canada’s latest signal has markets bracing for significant rate increases ahead. After holding rates steady at 2.25% in early September 2026, investors are now pricing in a nearly 90% probability of a December hike, with expectations for rates to climb to 3% by mid-2027.
This represents a meaningful shift in market expectations. Bets for 2027 hikes have intensified, with investors anticipating at least one 25-basis-point increase in January and potentially as many as three hikes by mid-year.
What This Means for BC Real Estate
For BC homebuyers, these anticipated rate increases carry real implications. Every 25-basis-point hike reduces borrowing power and raises the payment on variable-rate and renewing mortgages. On a $600,000 mortgage amortized over 25 years, each 25-basis-point increase adds roughly $75 to $85 a month depending on where rates start: about $74 moving from 2.25% to 2.50%, and about $82 moving from 4.00% to 4.25%. One distinction matters here: the Bank of Canada’s policy rate is not a mortgage rate. Variable rates are priced off lenders’ prime rate, which sits above the policy rate, and fixed rates follow bond yields, so the rate you are actually offered will be higher than the figure the Bank announces. Renewal pressure on existing mortgages comes on top of all of this.
The timing matters significantly. Homebuyers currently holding variable-rate mortgages or those planning to renew in 2027 face potential payment shocks. Fixed-rate holders locked in before these increases will benefit from rate certainty, but new entrants to the market will face higher borrowing costs.
Market Implications
Rising rates typically cool real estate demand by reducing affordability. BC’s market, already experiencing regional divergence and softness in certain segments, may see further pressure as carrying costs climb. Properties in price-sensitive segments could face downward pressure, while well-positioned properties in desirable locations may remain resilient.
Not all economists agree on the necessity of three hikes—some argue the pace seems excessive given economic conditions. This uncertainty itself creates planning challenges for buyers and sellers.
What You Should Do
If you’re considering a BC property purchase, understanding your true affordability at higher rates is critical. Lock in rate holds where possible. Federally regulated lenders already qualify you at the greater of your contract rate plus two percentage points or 5.25%; stress-test your own budget at least that hard, and against the payment you would face at renewal rather than against the policy rate.
Get a personalized property analysis or book a consultation with our team to develop a rate-aware strategy.
HOMS Real Estate Services Corp. is a technology, intelligence and multidisciplinary services company and is not a licensed real estate brokerage.Licensed real estate trading services are provided by Moji Dargahi, licensed real estate professional with Royal Pacific Realty Corp.HOMS is not an engineering firm: analysis outputs are preliminary screening estimates for informational purposes and are not sealed engineering documents. Tool outputs are estimates for informational purposes only and do not constitute an appraisal, recommendation, financial advice or legal advice.